
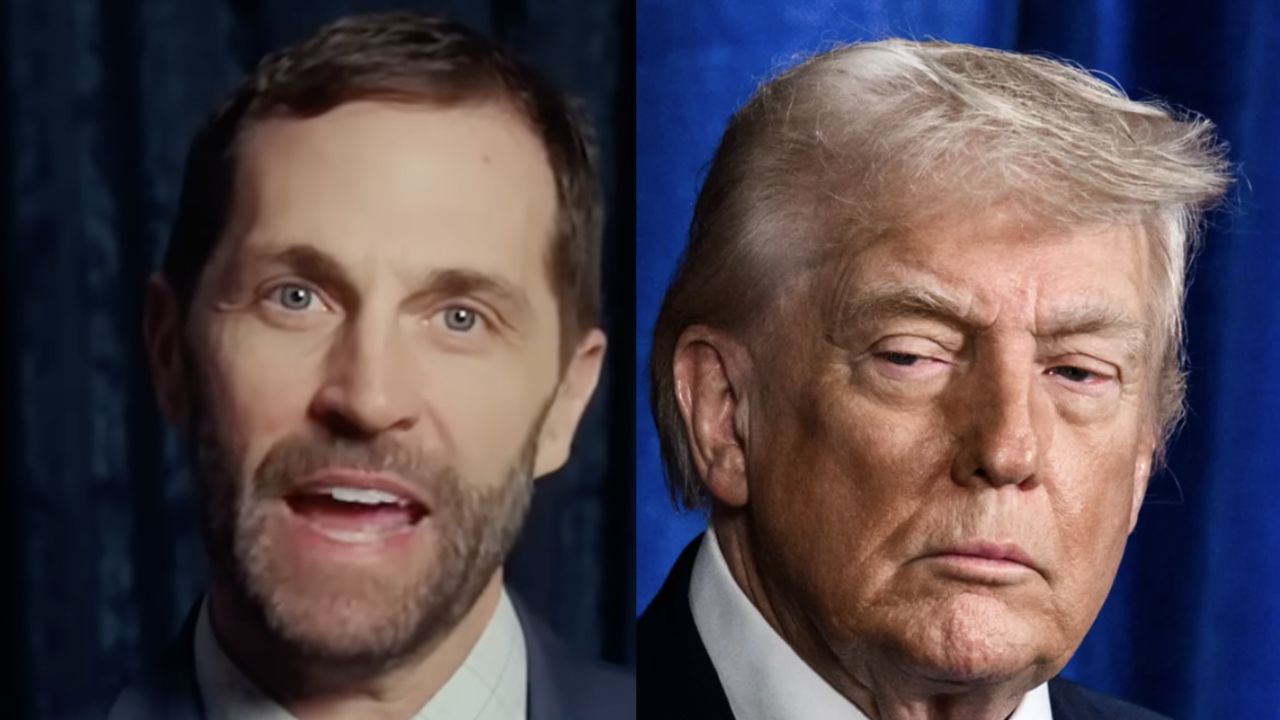
U.S. Representative Jason Crow (D-Colo.) called out President Donald Trump on Wednesday over a decade-old campaign promise to eliminate the national debt, pointing to new Treasury Department figures showing the nation’s total debt has now surpassed $40 trillion for the first time in history.
In a post on X published at 4:48 p.m. on August 19, 2026, Crow wrote in full:
“In 2016, Trump said he’d get rid of the national debt ‘fairly quickly.’
A decade later, America’s debt just hit $40 TRILLION.
The Republican One Big Ugly Bill adds over $4 trillion alone—all to shamefully give tax breaks to billionaires and corporations.”
Debt Crosses Historic Threshold
Crow’s post came the same day the Treasury Department confirmed that total U.S. public debt outstanding had reached $40.047 trillion as of Tuesday, a figure that includes $32.266 trillion in Treasury securities held by the public and $7.782 trillion in intra-governmental debt holdings, according to Reuters.
CNBC reported that the milestone arrived roughly four and a half years after the debt first topped $30 trillion, and that ten years earlier the debt stood at $19.4 trillion — meaning the figure has more than doubled in a decade, the exact timeframe Crow referenced in his post.
The 2016 Promise
Crow’s post directly referenced comments Trump made during his first presidential campaign in 2016, when he pledged to eliminate the national debt “fairly quickly” if elected. At the time, the national debt stood at just under $20 trillion. It has instead grown by more than $20 trillion in the years since, spanning both the Trump and Biden administrations.
Debt Growth Under Two Administrations
According to Reuters, public debt rose by $7.8 trillion during Trump’s first term, with more than half of that increase accumulating during the pandemic response in the final nine months of his presidency. Since beginning his second term in January 2025, the debt load has grown by another $3.8 trillion, bringing his combined two-term total to roughly $11.6 trillion in added debt.
Public debt increased by $8.4 trillion during President Joe Biden’s term in office, a rise driven in part by continued COVID-19 recovery spending as well as infrastructure investment and clean energy subsidies championed by his administration.
“One Big Ugly Bill” and the $4 Trillion Question
Crow’s post singled out what he called the “Republican One Big Ugly Bill” — a reference to Trump’s second-term legislative package, formally titled the One Big Beautiful Bill Act — for adding what he described as “over $4 trillion” to the national debt. According to the nonpartisan Congressional Budget Office, the legislation is projected to add $4.7 trillion in debt.
Crow characterized the spending in the bill as benefiting wealthy individuals and corporations, writing that the added debt exists “all to shamefully give tax breaks to billionaires and corporations.”
Fiscal Watchdogs Sound the Alarm
The $40 trillion threshold drew immediate warnings from budget watchdog organizations. Maya MacGuineas, president of the nonpartisan Committee for a Responsible Federal Budget, said in a statement that the debt’s effects extend beyond government ledgers and into household finances, cautioning that continued borrowing worsens inflation and crowds out other budget priorities.
MacGuineas noted that the debt reached $40 trillion less than five months after crossing the $39 trillion mark, and that it has quadrupled in under 20 years, despite taking until 1981 to first reach $1 trillion.
Market Reaction and Treasury Response
The debt milestone has coincided with turbulence in the bond market. Reuters reported that yields on long-term Treasury bonds hit their highest levels in nearly two decades this week, following a $25 billion auction of 30-year bonds that priced at the highest yield since 2021. Treasury Secretary Scott Bessent announced Wednesday that the department would double the size of its debt buybacks for 10- to 30-year Treasuries to at least $4 billion per operation, an effort aimed at pushing long-term yields back down.
Trump’s Response
Asked at the White House on Wednesday whether Americans should be concerned about bond market volatility, Trump downplayed the risk, saying the country remains strong and that current interest rates are “ridiculous,” while calling for rates to come down as the country’s economic position strengthens.
Deficit Figures Add to the Picture
The Treasury Department’s most recent monthly accounting showed a $432.3 billion deficit for July, the highest monthly total since March 2021. Year-to-date, the deficit is nearing $1.8 trillion, running higher than the same period the previous year and already exceeding the full-year deficit total for fiscal 2025 with two months still remaining in the current fiscal year.
Interest Costs Now Rival Major Federal Programs
Interest payments on the national debt have totaled nearly $1.2 trillion so far this year, making debt service the second-largest line item in the federal budget behind Social Security, and now surpassing Medicare spending, according to Reuters. The 2025 fiscal year had already marked the first time debt service costs exceeded Pentagon funding.
Rising Costs for Consumers
Higher yields on long-term Treasury bonds tend to translate into higher borrowing costs for everyday Americans, including mortgage rates, auto loans and commercial lending. With the debt continuing to climb and no clear resolution to rising yields, analysts have pointed to the growing strain on federal finances as a factor that could ripple into household budgets nationwide.
A Pattern of Congressional Scrutiny
Crow’s statement adds to a broader pattern of congressional Democrats scrutinizing the Trump administration’s fiscal and spending decisions in recent months. His post reflects continued Democratic criticism of the One Big Beautiful Bill Act, which has drawn opposition from lawmakers who argue it favors high-income earners and corporations while adding significantly to the federal debt burden.
Looking Ahead
With the U.S. debt load now exceeding $40 trillion and interest costs consuming an increasing share of the federal budget, the fiscal trajectory is expected to remain a central point of political debate in Washington. Budget watchdogs have continued to press lawmakers from both parties to address the imbalance between federal spending and revenue, warning that inaction could heighten the risk of a broader fiscal crisis in the years ahead.